Plant and machinery finance
Compare Plant &
Machinery Finance
What we do
Compare Advantage is a free comparison service for contractors and manufacturers. Tell us the machine and the price, and our partner, FCA-authorised broker Halo Corporate Finance, checks it against the 130+ lenders on its panel, including specialists in used plant. You can compare the answer with the dealer’s finance before you sign.
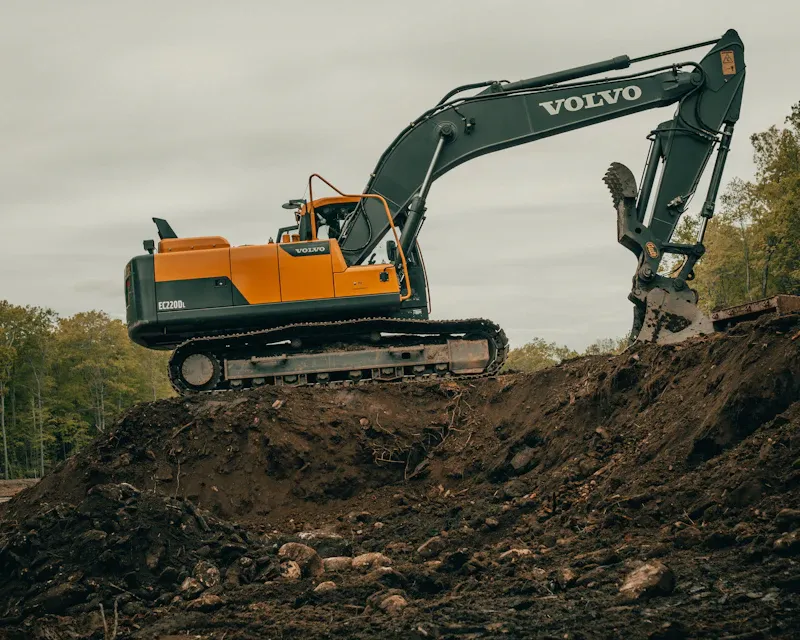
- Excavators, dumpers, telehandlers, rollers and attachments
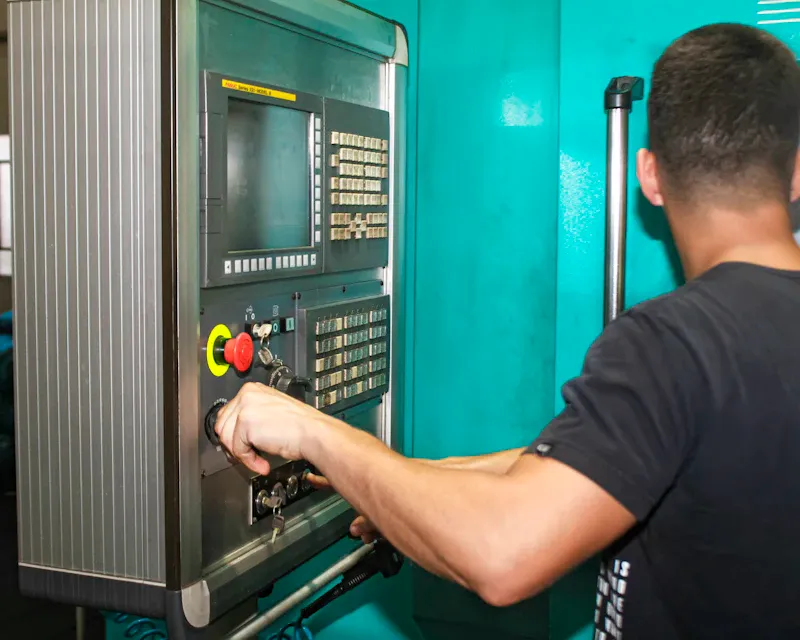
- CNC, fabrication and production machinery
- New, used, auction or private sale
Prefer to talk? Call 0330 057 7175
- 130+ lendersOn our partner’s panel
- £5k to £1mLoans and asset finance
- One enquiryInstead of one per lender
- FCA-authorised partnerHalo Corporate Finance
- Free to enquireNo obligation to apply
Compare before you apply
Get finance lined up before the machine is chosen
Most plant finance is agreed in the yard. The contract is won, the start date is close, the dealer has a machine and a finance quote, and it gets signed because there is no time to look elsewhere. The machine might be right, but the finance is one lender’s price. Contractors who start the finance when the tender goes in, not when the machine arrives, have time to compare, and something to put against the dealer’s offer.
- 1
Tell us once
Two minutes on the form: how much, what it is for and a few details about the business.
- 2
The panel is checked
Halo Corporate Finance matches your enquiry against the 130+ lenders on its panel.
- 3
You choose
Halo talks you through the options that fit. You decide whether to apply. There is no obligation.
What to compare
- The dealer’s quote against the panel, on the same machine, deposit and term, so the difference is the lender and nothing else.
- The age of the machine at the end of the term. Many lenders cap how old a machine can be when the last payment falls due. That decides the longest term you can have on used kit.
- Hire purchase against refinancing what you already own. If the fleet is paid off, releasing cash from it can fund the next machine without a new deposit.
- What happens if the contract is delayed. Ask whether the first payment can be deferred, or whether repayments can follow the seasons if winter is quiet.
- Fees on top of the instalments, including documentation, option-to-purchase and any charge for settling early when you upgrade.
From tender to site
When to start the finance
Plant is bought against a start date. The earlier the finance starts, the more choice you have when the date arrives.
- 1
The tender goes in
Price the machine into the job and send us the spec. You will know roughly what lenders on the panel need before you are committed.
- 2
The contract is won
With the paperwork already gathered, the enquiry goes straight to the lenders most likely to fund that machine at that age.
- 3
The machine is chosen
Main dealer, independent or auction. The lender may want the serial number, hours, a photo or an inspection on used kit.
- 4
Terms are agreed
You compare what comes back with the dealer’s own finance and choose. Nothing is signed until you decide.
- 5
The machine is on site
The lender pays the supplier, the machine is delivered and you pay monthly from the work it is doing.
What you can finance
Machine by machine
Lenders on the panel fund the whole range, from a one-tonne micro digger to a production line. What changes from one machine to the next is how the lender judges its value.
Excavators and diggers
Micro and mini diggers through to 20-tonne-plus tracked machines. Popular makes and models with a strong resale market are the easiest to fund used.
Dumpers and site transport
Forward-tipping and swivel dumpers, tracked carriers and site vans. Often bought alongside a digger, so one agreement can cover both.
Telehandlers and access
Telehandlers, cherry pickers and scissor lifts. Hours and service history matter a great deal to a lender on used access equipment.
Rollers, crushers and screeners
Compaction, crushing and screening equipment for civils, demolition and recycling. Higher values, so lenders look closely at the work it will do.
Attachments
Breakers, buckets, tilt rotators and quick hitches. Can be added to the main machine’s agreement or financed on their own once the value justifies it.
Production machinery
CNC machining centres, lathes, press brakes, lasers and packaging lines. Lenders may include delivery and installation where the supplier invoices it.
Used plant
How a lender values a used machine
With plant finance, the machine is the lender’s security. If payments stop, the lender recovers it and sells it. So the question every lender asks about a used machine is simple: what would it fetch, and for how long?
That is why two machines at the same price can get very different offers. It is also why it pays to send the details of the actual machine, not just “a used 8-tonner”: the lender can only price what it can see.
If you are choosing between two machines, ask for both to be checked. The cheaper one to buy is not always the cheaper one to finance.
Age
A lender works out how old the machine will be when the agreement ends. The older it is now, the shorter the term on offer, and some lenders will not fund past a set age at all.
Hours
Hours on the clock tell a lender more than the year. A low-hours older machine can be easier to fund than a newer one that has worked double shifts.
Make and resale market
Machines from manufacturers with a deep used market keep their value, which is what the lender is relying on if payments stop. Rare or highly specialised kit is harder.
Where it comes from
Main dealers are the most straightforward. Independent dealers, auctions and private sales are all possible, with checks that the seller owns it and there is no finance outstanding.
Plant finance in figures
Construction runs on financed machines
Plant and machinery is one of the largest parts of UK asset finance, and it grew strongly through 2026.
£7.8bn
of plant and machinery finance written for UK businesses in 2025
+30%
growth in plant and machinery finance in August 2026 against a year earlier
885,000
small and medium-sized construction businesses, the largest SME sector in the UK
Sources: Finance & Leasing Association, new business figures for 2025 and August 2026; Department for Business and Trade, Business Population Estimates 2025.
Your business
What lenders want to see from a contractor
The machine is half the decision. The other half is whether the business can keep up the payments, and lenders who specialise in construction know how the industry’s cash flow works: stage payments, retentions and a quieter winter.
- Two years of accounts, or management figures if you are newer
- Recent business bank statements, to see the money coming in
- The contracts or regular customers the machine will work for
- Your existing fleet, and any finance already on it
- A clean record with HMRC, including Construction Industry Scheme returns
- The quote or invoice for the machine, with serial number and hours if used
Having these ready when the contract is won is the single biggest thing that speeds up an approval.
Already own a fleet?
Use the machines you own to buy the next one
Many contractors own most of their fleet outright. That is value sitting on site. Refinancing releases cash against machines you already have, while you keep working them, and it can be used for a deposit on new kit, a wage bill while you wait for a stage payment, or a VAT or tax bill.
Choose Release cash from machines I own on the form and list the machines. The lender will want the same details as for a purchase: make, model, year and hours.
For manufacturers
Production machinery is often bought from overseas, with a deposit to the manufacturer months before delivery. Some lenders can fund staged payments, and the cost of installation, so the whole project goes on one agreement instead of draining working capital for months.
Tax relief on the machine
On hire purchase, your business can usually claim capital allowances once the machine is in use, including the £1 million Annual Investment Allowance. Companies buying new, unused machinery may claim full expensing. Second-hand machines do not qualify for full expensing but can qualify for the Annual Investment Allowance. Check the details with your accountant.
Questions
Plant finance questions
Need a tipper or a van as well? See commercial vehicle finance. For workshop, IT and other kit, see equipment finance.
Compare plant financeWhat is plant and machinery finance?
It is asset finance for construction plant and production machinery. A lender buys the machine, or lends against it, and you pay monthly while you use it. The machine itself secures the agreement, which is why it is often easier to arrange than an unsecured loan of the same size.
Can I finance a used excavator?
Yes. Used plant is one of the most commonly financed assets. The lender will look at the age, hours, make and condition, and will usually limit the term so the machine is not too old by the time it is paid off.
How old can a used machine be?
It depends on the lender and the type of machine. Most work out the age at the end of the agreement rather than today, so an older machine usually means a shorter term. Popular makes with a strong used market can be funded at older ages than specialist kit.
Can I buy plant at auction with finance?
Often, yes, but arrange it before the sale. Auction terms usually need payment within days, so you want the lender to have approved you and agreed a maximum before you bid.
Do I need a deposit for plant finance?
Not always. Established contractors with good accounts may be offered agreements with only the first payment in advance. Newer businesses, or older machines, are more likely to need a deposit or a part-exchange.
Can I finance several machines at once?
Yes. A digger, dumper and attachments for the same contract can go on one agreement or several, and some lenders will set a facility you can draw on as you add to the fleet.
Can I raise cash against plant I already own?
Yes. That is asset refinance. A lender advances money against machines you own outright, or have nearly paid off, and you keep using them. The cash can fund a new machine, a tax bill or working capital for a big job.
Is hire purchase or leasing better for plant?
Contractors usually choose hire purchase for plant, because they want to own and keep the machine for years and claim the capital allowances. Leasing can suit machinery that is replaced on a fixed cycle. Our hire purchase vs finance lease guide sets out the differences.
Can a new construction business get plant finance?
Some lenders on the panel will, particularly for popular machines with a strong resale value. Expect to be asked for a deposit, a personal guarantee or evidence of the work lined up, such as a contract or a letter of intent.
Does finance cover delivery, installation and training?
For production machinery, many lenders will include delivery and installation when they appear on the supplier’s invoice. Ask for it in the enquiry so the lender prices the whole cost, not just the machine.
How quickly can plant finance be arranged?
A popular machine from a main dealer, for a contractor with up-to-date accounts, can move within days. Used, auction and private-sale machines take longer, because the lender checks the asset and the seller as well as the business.
Sources
- Finance & Leasing Association: asset finance new business grew by 1% in 2025
- Finance & Leasing Association: asset finance new business grew by 10% in August 2026
- Department for Business and Trade: Business population estimates 2025
- GOV.UK: Capital allowances when buying on hire purchase or leasing
- GOV.UK: Check if you can claim full expensing
- FCA register: Halo Corporate Finance Ltd (FRN 726655)
Written by the Compare Advantage team, Chorley. Facts checked against the sources above on 4 November 2026. This page is general information, not financial advice.
Compare Advantage Ltd (FRN 1028452, company no. 14289362) is an Introducer Appointed Representative of Halo Corporate Finance Ltd (FRN 726655). We introduce business finance enquiries to Halo. We are not a lender and do not give financial advice. If you take out finance, the lender may pay commission to Halo Corporate Finance, and Halo may pay us a fee for the introduction. Finance is subject to status and is available to UK businesses only.